

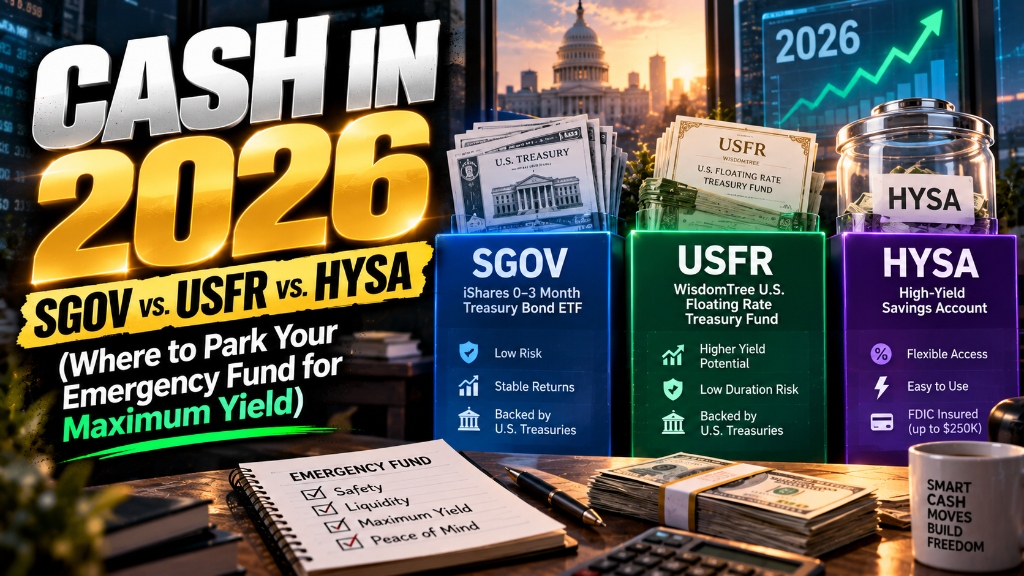
Cash in 2026: SGOV vs. USFR vs. HYSA (Where to Park Your Emergency Fund for Maximum Yield)
Compare SGOV vs USFR vs HYSA for cash reserves. Discover state tax exemptions, T+1 settlement, and the optimal 3-tier emergency fund cash yield blueprint.
Educational Resource: This guide does not constitute financial or legal counsel.
Direct Answer: Comparing SGOV vs USFR vs HYSA for cash reserves reveals that ultra-short Treasury ETFs (SGOV and USFR) consistently outperform traditional High-Yield Savings Accounts for residents of high-tax states. Because Treasury fund distributions are 100% exempt from state and local income taxes, they deliver a higher net after-tax yield while maintaining near-instant liquidity through standard T+1 settlement.
Holding cash used to be simple: you opened a high-yield savings account (HYSA) at an online bank, transferred your emergency fund, and collected interest without thinking twice.
In today’s economic environment, however, parking large cash buffers in retail banking accounts leaves substantial money on the table. Online banks quietly skim profit margins off cash yields, delay interest rate bumps, and subject your entire return to burdensome state and local income taxes.
For savers holding $20,000, $50,000, or six figures in emergency funds or home-down-payment savings, ultra-short Treasury ETFs like SGOV (iShares 0-3 Month Treasury Bond ETF) and USFR (WisdomTree Floating Rate Treasury Fund) have rewritten the rules of cash management.
Here is the exact mathematical breakdown comparing SGOV, USFR, and traditional HYSAs, how state tax exemptions create superior after-tax yields, and how to structure a three-tier cash architecture.
The Flaws of Modern HYSAs: Lagging Rate Drops and Discretionary Bank Spreads
Modern High-Yield Savings Accounts suffer from discretionary bank interest rate spreads and complete exposure to state and local income taxes.
When the Federal Reserve adjusts its benchmark federal funds rate, commercial banks do not pass yields directly to retail depositors. Instead, banks widen their net interest margin (the difference between what they earn by investing your cash and what they pay you in interest). When rates drop, banks slash HYSA APYs overnight; when rates climb, banks drag their feet for months before nudging customer yields upward.
Furthermore, retail HYSAs present two major structural drawbacks:
- Full State and Local Tax Drag: Every dollar earned in a standard bank savings account is fully subject to federal, state, and city income taxes. For a resident of California, New York, or Massachusetts in an upper tax bracket, state taxes consume up to 9% to 13.3% of annual cash earnings.
- FDIC Insurance Ceilings: Retail bank accounts insure deposits only up to $250,000 per depositor, per insured institution. Managing cash buffers above this limit requires opening accounts across multiple institutions or relying on complex sweep networks.
How 0–3 Month Treasury ETFs (SGOV and USFR) Function Under the Hood
Ultra-short Treasury ETFs invest exclusively in short-dated United States government debt obligations backed by the full faith and credit of the federal government.
Rather than buying individual Treasury bills on TreasuryDirect and manually constructing rollover ladders, investors can purchase shares of exchange-traded funds that automate the entire process for an expense ratio of less than 0.15%:
SGOV (iShares 0-3 Month Treasury Bond ETF)
SGOV invests in fixed-rate U.S. Treasury bills with remaining maturities of three months or less. The fund’s managers constantly purchase newly auctioned short-term bills and hold them until maturity. Because these debt instruments mature in under 90 days, SGOV has virtually zero duration risk: its share price fluctuates by mere pennies (typically oscillating between $100.00 and $100.50 as monthly dividends accrue and pay out).
USFR (WisdomTree Floating Rate Treasury Fund)
USFR invests in two-year U.S. Treasury Floating Rate Notes (FRNs). Unlike fixed-rate notes, the coupon rate on an FRN resets every single week based on the highest accepted discount rate of the most recent 13-week Treasury bill auction. This weekly reset mechanism eliminates interest rate duration risk almost entirely, allowing USFR to adjust immediately to shifting monetary policy.
Both funds trade on major stock exchanges, distribute dividends monthly, and carry direct backing from the United States Treasury, making default risk virtually identical to FDIC-insured bank balances.
The State Tax Exemption Math: Calculating Your Effective Tax-Equivalent Yield
Income generated from U.S. Treasury obligations is exempt from state and local income taxes under 31 U.S. Code Section 3124, creating a massive tax-equivalent yield advantage over bank accounts.
To compare an HYSA yield against a Treasury fund like SGOV or USFR, you must compute the Tax-Equivalent Yield (TEY) based on your state marginal income tax rate:
Tax-Equivalent Yield (TEY) = Treasury Fund Yield / (1 − State Marginal Tax Rate)
Consider an investor evaluating a 5.00% SEC yield on SGOV versus a top-tier retail HYSA offering 4.60% APY in three different state tax environments:
- Texas or Florida (0% State Tax Rate): The tax-equivalent yield equals the nominal yield (5.00%). SGOV beats the 4.60% HYSA by 40 basis points purely on institutional pricing efficiency.
- New York State + NYC Resident (10.5% Combined State & City Bracket):
TEY = 5.00% / (1 - 0.105) = 5.58%An HYSA would need to pay 5.58% APY just to match SGOV’s after-tax return. - California Resident (11.3% Marginal State Bracket):
TEY = 5.00% / (1 - 0.113) = 5.63%The California investor earns an extra 103 basis points in net after-tax yield by holding SGOV over the 4.60% savings account.
On a $100,000 cash reserve, that state tax exemption puts an additional $1,000+ of risk-free cash directly into your pocket every single year.
Comparison Table: SGOV vs. USFR vs. Leading HYSAs
| Evaluation Metric | iShares SGOV ETF | WisdomTree USFR ETF | Top-Tier Online HYSA |
|---|---|---|---|
| Underlying Asset | 0–3 Month U.S. T-Bills | 2-Year Floating Rate Notes | Bank General Deposits |
| Credit Backing | Full Faith & Credit of U.S. | Full Faith & Credit of U.S. | FDIC Insured ($250k Limit) |
| State & Local Income Tax | 100% Tax-Exempt | 100% Tax-Exempt | 100% Taxable |
| Expense Ratio | 0.07% net fee | 0.15% fee | Hidden in interest spread |
| Dividend / Interest Frequency | Monthly dividend distribution | Monthly dividend distribution | Monthly interest compounding |
| Settlement Liquidity | T+1 Market Days (Next Day) | T+1 Market Days (Next Day) | ACH Transfer (1–3 Days) |
| Price Volatility | Minimal ($100 base) | Minimal ($50 base) | Fixed $1.00 net asset value |
| Access Channel | Any brokerage account | Any brokerage account | Specific bank app/portal |
Liquidity Showdown: T+1 Settlement Speeds vs. Instant Bank Transfers
With the financial markets shifting to T+1 settlement cycles, selling Treasury ETF shares makes funds available for transfer the very next business day.
A common objection to holding cash reserves in brokerage ETFs is liquidity access: “What happens if my car breaks down or my furnace dies on a Saturday?”
In reality, Treasury ETFs are often more accessible than secondary online savings accounts:
- Credit Cards Cover Immediate Emergencies: True emergencies (hospital admissions, car repairs, emergency travel) are paid with a credit card at the point of sale. You do not hand a car mechanic an envelope of ACH cash; you swipe a credit card, granting you a 25- to 30-day interest-free grace period before the statement bill comes due.
- Next-Day Settlement (T+1): U.S. equities and ETFs settle on a
T+1basis (trade date plus one business day). If you sell $10,000 of SGOV on Monday morning, the trade settles and the cash is fully available to initiate an electronic transfer to your checking account by Tuesday morning. - Brokerage Cash Management Features: Major discount brokerages like Fidelity, Charles Schwab, and Vanguard offer debit cards and check-writing features connected directly to your brokerage settlement account, allowing instant access to settled cash without external bank transfers.
The Optimal 3-Tier Emergency Fund Architecture (Checking + HYSA + SGOV)
The most resilient cash management structure uses a three-tier system balancing immediate transaction liquidity with maximum after-tax yield.
Rather than dumping all cash into a single account, organize your liquid reserves across three distinct operational layers:
Tier 1: Working Operational Checking (1 Month of Expenses)
Keep exactly one month of normal living expenses plus a $1,000 buffer inside your primary bank checking account. This tier handles daily debit swipes, automatic credit card autopays, and recurring mortgage or rent checks. Yield here is irrelevant; frictionless transaction processing is the objective.
Tier 2: Liquid Instant Cash Reserve (1 to 2 Months of Expenses)
Park one to two months of basic living costs inside an established online HYSA linked directly to your checking account. This buffer exists to handle sudden expenses that cannot wait for ETF market settlement, such as a contractor requiring a direct wire or an immediate personal check.
Tier 3: Core Wealth Preservation Vault (3 to 6+ Months of Expenses in SGOV/USFR)
House the bulk of your emergency reserves, tax set-asides, and intermediate savings inside SGOV or USFR within a low-cost brokerage account. This capital works continuously at institutional yields, protected from state income taxation, while remaining one business day away from deployment.
Step-by-Step Purchase Guide on Major Discount Brokerages
Purchasing SGOV or USFR takes less than sixty seconds on Fidelity, Charles Schwab, or Vanguard.
To execute your first cash allocation, follow this streamlined walkthrough:
- Log into Your Brokerage Account: Open your existing taxable investment account or individual brokerage window.
- Open the Trade Ticket: Click the
Tradebutton and enter the ticker symbolSGOVorUSFR. - Choose Order Action & Type: Select
Buy. Set the order type toLimit Orderand set your limit price equal to the current Ask or the midpoint price (e.g., $100.35) during standard market trading hours (9:30 AM to 4:00 PM Eastern). Avoid buying after-hours to ensure tight bid-ask spreads. - Select Reinvestment Preference: In your account settings, verify whether you prefer dividends automatically reinvested into new shares or deposited as cash into your core money market fund.
- Confirm and Transact: Review the total dollar value and submit your order.
Frequently Asked Questions
Is SGOV better than an HYSA in high-tax states?
Yes, SGOV is significantly better than an HYSA in high-tax states like California, New York, New Jersey, and Massachusetts because its dividends are exempt from state and local income taxes, yielding 50 to 120 basis points more on an after-tax equivalent basis.
Can you lose money investing in SGOV or USFR?
The probability of principal loss in SGOV or USFR is near zero because both funds invest in ultra-short U.S. government debt maturing in under three months. Minor daily price changes reflect accrued interest that is paid out monthly as cash dividends.
What is the difference between SGOV and USFR?
SGOV invests in fixed-rate Treasury bills maturing in zero to three months, making it sensitive to where short-term T-bill yields currently stand. USFR invests in two-year Floating Rate Notes that reset their yield weekly, allowing it to adapt to interest rate adjustments faster.
How do I report SGOV state tax exemptions on my taxes?
At year-end, your brokerage issues IRS Form 1099-DIV showing total dividends in Box 1a. Your brokerage provides an accompanying supplemental statement listing the exact percentage of income derived from U.S. Government Obligations (typically 95% to 100% for SGOV), which you enter on your state tax return to subtract that income from state taxable earnings.
How often do SGOV and USFR pay dividends?
Both SGOV and USFR calculate dividends daily and pay cash distributions monthly, typically declaring ex-dividend dates in the first week of each calendar month.
Final Thoughts: Stop Leaving Cash Yield on the Table
Treating cash preservation as an afterthought costs serious money over time.
By migrating your core emergency reserves out of traditional bank accounts and into institutional Treasury ETFs like SGOV or USFR, you eliminate arbitrary bank rate cuts, insulate your earnings from state income taxation, and maintain sovereign-backed security.
Review your liquid cash reserves today, calculate your personal state tax-equivalent yield, and upgrade your cash engine to work as hard as your long-term portfolio.
Download: The 2026 Wealth Compounding & FIRE Planning Toolkit
Our complete spreadsheet model and 28-page strategic handbook covering asset allocation buckets, Indian inflation adjustments, and long-term SIP compounding.
- Interactive FIRE & Net Worth Excel/Sheets model
- Asset allocation & emergency reserve matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Aditya Singhania
Verified AuthorAditya writes about investing, saving habits, and smart money management. With a background in financial planning, he helps readers build simple, reliable wealth habits for the long run.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search empirical insights, explore our four wisdom categories, and discover curated strategic essays.
Search Insights
Recent Essays
The Backyard Cash Flow Engine: How to House Hack with an ADU in 2026
11 min read • Oct 20How to Become a Fractional COO: Landing Your First $5,000/Month Retainer Client
12 min read • Oct 20The Zero-Bounce Outbound Engine: How to Set Up Multi-Domain Cold Email with Instantly and Clay
12 min read • Oct 20Featured Guides
Further Wisdom & Insights
Explore All Articles
How to Build a 4-Week T-Bill Ladder on TreasuryDirect (Step-by-Step)
Learn how to build a 4-week Treasury bill ladder on TreasuryDirect. Maximize state-tax-exempt yields, automate reinvestments, and preserve weekly cash liquidity.
The Backyard Cash Flow Engine: How to House Hack with an ADU in 2026
Master the ADU house hacking strategy. Learn how building a backyard accessory dwelling unit can offset 70% to 100% of your primary mortgage payment.
Direct Indexing vs. Index Funds: Is Automated Tax-Loss Harvesting Worth the Fee for Retail Investors?
Compare direct indexing vs index funds tax loss harvesting math. Uncover advisory fee drag, tax alpha decay, account minimums, and tracking error risks.