

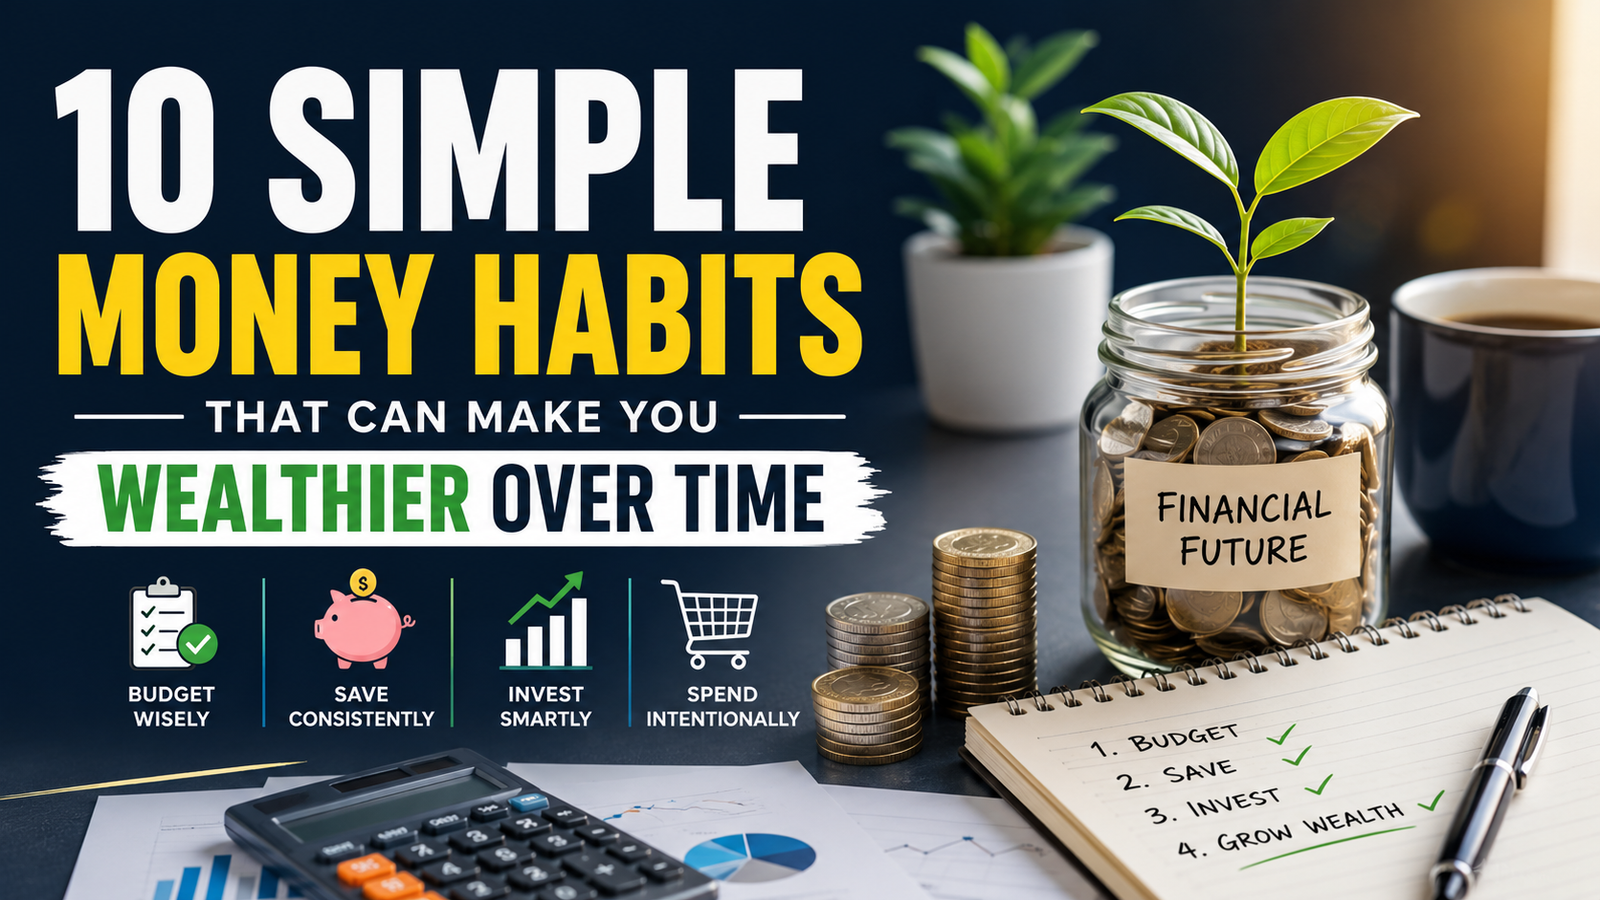
10 Simple Money Habits That Can Make You Wealthier Over Time
Discover 10 simple money habits that help you build wealth over time through smarter saving, budgeting, and intentional spending decisions.
Educational Resource: This guide does not constitute financial or legal counsel.
Building real wealth doesn’t come from hitting a lucky stock pick or inheriting a sudden fortune. It comes from small daily habits repeated month after month until your money starts working harder than you do.
Wealth accumulation is driven primarily by consistent, daily financial discipline rather than high initial income. By automating savings, tracking expenses, adhering to a structured budget, avoiding lifestyle inflation, and maintaining an emergency fund, anyone can build a stable financial foundation and compound net worth over time.
What are simple money habits?
Simple money habits are repeatable financial routines that steadily strengthen your net worth and cash flow management.
Rather than requiring complex trading strategies or extreme lifestyle sacrifices, these habits instill operational discipline around how you earn, save, allocate, and invest capital. Minor optimizations done month after month build genuine financial freedom.
The 10 Essential Money Habits That Build Wealth
If you want your money working for you instead of against you, these 10 habits are non-negotiable.
1. Pay Yourself First
Automate your savings by transferring a set percentage of your income to investment or savings accounts immediately upon receiving your paycheck. Treating savings as a non-negotiable fixed liability guarantees consistent capital accumulation before discretionary spending occurs.
2. Track Every Outflow
Track your daily spending. Seriously. It’s eye-opening to see where your money actually vanishes every week. Use a simple app or spreadsheet to catch subscription leaks and impulse buys.
3. Maintain a Structured Budget
Give every dollar a clear job before the month starts. A structured budget isn’t about deprivation; it gives you total control over your bills, savings targets, and spending limits.
4. Implement a Cooling-Off Period for Purchases
Give yourself a cooling-off period before buying non-essentials. Wait 24 hours for small impulse items and 30 days for major purchases to make sure you actually need them.
5. Build a Tiered Emergency Reserve
Keep a solid cash buffer in a high-yield savings account. Having 3 to 6 months of living expenses stashed away keeps you from being forced to sell off stocks during a market dip.
6. Cap Lifestyle Inflation
When you get a raise or bonus, funnel it straight into investments instead of upgrading your lifestyle. Let your net worth grow faster than your monthly bills.
7. Conduct Weekly Financial Audits
Take 15 minutes every Sunday to review your accounts, check upcoming bills, and track your savings milestones.
8. Optimize Credit Management
Use credit cards like debit cards and pay the full balance every single month without fail. You get the cashback rewards without paying a penny in high-interest debt.
9. Define Explicit Financial Targets
Pick exact financial numbers to hit instead of setting vague goals. Clear targets keep you motivated and accountable every single day.
10. Commit to Continuous Financial Education
Spend 15 minutes a day reading about finance and investing. Expanding your financial knowledge yields compounding dividends for the rest of your life.
Strategic comparison: Financial Habits Impact Matrix
| Money Habit | Execution Frequency | Primary Financial Benefit | Implementation Complexity | Compounding Horizon |
|---|---|---|---|---|
| Pay Yourself First | Monthly (Automated) | Guarantees Capital Accumulation | Low | High (Multi-Year) |
| Expense Tracking | Daily | Eliminates Cash Leaks | Low | Immediate |
| Lifestyle Inflation Cap | Annual / Per Raise | Maximizes Net Worth Growth | Medium | Exponential |
| Emergency Fund Setup | One-Time / Ongoing | Prevents Forced Asset Sales | Medium | Immediate Protection |
Frequently asked questions
what’s the single most effective daily financial habit?
Tracking every expense daily is the most effective habit because it builds immediate awareness around spending behavior and highlights unnecessary leaks.
How much of my monthly income should I ideally save?
Targeting 20% of net income is a standard benchmark, though starting with any consistent percentage and scaling upwards over time builds the necessary habit loop.
Can small daily savings genuinely lead to long term wealth?
Yes, small savings compounded over decades through disciplined index investing or high yield vehicles create significant capital growth due to the math of compound interest.
How long does it take for a new money habit to become automatic?
Most behavioral studies indicate that financial habits require approximately 30 to 60 days of consistent practice before becoming automatic routines.
Why is an emergency fund essential before investing heavily in stocks?
An emergency fund protects long term investments, ensuring you never have to liquidate stocks at a loss during a market crash to cover sudden emergency expenses.
what’s lifestyle inflation and why is it dangerous?
Lifestyle inflation occurs when spending increases at the exact same rate as income growth, effectively locking individuals into a paycheck to paycheck cycle despite earning higher salaries.
Should I pay off all debt before building emergency savings?
You should build a baseline one-month emergency cushion before aggressively paying off debt to avoid relying on credit cards when unexpected expenses occur.
Conclusion
Building wealth comes down to simple daily habits repeated consistently over time. Pick just one habit from this list today - like automating your savings - and put it into action. Over time, these small decisions compound into serious financial freedom.
Download: The 2026 Wealth Compounding & FIRE Planning Toolkit
Our complete spreadsheet model and 28-page strategic handbook covering asset allocation buckets, Indian inflation adjustments, and long-term SIP compounding.
- Interactive FIRE & Net Worth Excel/Sheets model
- Asset allocation & emergency reserve matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Aditya Singhania
Verified AuthorAditya writes about investing, saving habits, and smart money management. With a background in financial planning, he helps readers build simple, reliable wealth habits for the long run.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search empirical insights, explore our four wisdom categories, and discover curated strategic essays.
Search Insights
Recent Essays
The Backyard Cash Flow Engine: How to House Hack with an ADU in 2026
11 min read • Oct 20How to Become a Fractional COO: Landing Your First $5,000/Month Retainer Client
12 min read • Oct 20The Zero-Bounce Outbound Engine: How to Set Up Multi-Domain Cold Email with Instantly and Clay
12 min read • Oct 20Featured Guides
Further Wisdom & Insights
Explore All Articles
Navigating Tax Efficiency for High Earning Professionals
Legal asset location, tax-deferred accounts, and entity structuring strategies to preserve capital for high-earning executives and founders.
How to Manage Cash Flow in a Solo Business
A practical financial operating system for solopreneurs to smooth out uneven income cycles, automate tax reserves, and build personal wealth.
Building a Bulletproof Emergency Fund in Volatile Markets
How high earners structure liquid cash reserves across tiered yield accounts to preserve purchasing power during economic downturns.